
Bookshop guide
A learning path for a bookshop, new or running: job titles, books with ISBNs, authors' books on consignment, school prices, practice, opening balances.
On this page
- A new business
- Who does what
- 1. Shop details and users
- 2. Master data
- 3. Starting capital, purchases and consigned books
- 4. A day of selling
- 5. Consignors, receivables and payables
- 6. Reports per job title
- 7. Checklists
- A running business
- 1. Master data
- 2. Practice for the team
- 3. Emptying the practice transactions
- 4. Opening balances
- 5. Check before going live
- 6. Going live
This guide is for the team setting up Vende at a bookshop that sells published books and consigned books to buyers who walk in and to schools. It has two parts: A new business for a shop just opening, with no stock, receivables or payables from before, and A running business for one moving to Vende, with team practice and opening balances. The example is Toko Buku Cahaya Ilmu. The names of the shop, customers, suppliers, consignors and people and all the figures are made up.
What the business looks like:
- Published books: bought from a distributor on 30 days' credit, sold per copy. Every book already has an ISBN barcode on its cover.
- Consigned books: local authors and small publishers leave their books with the shop. The shop pays only for the books sold (consignment).
- Selling: buyers come to the till; schools buy textbooks at a discount and pay 30 days later.
- Store room: books from the distributor are received without seeing the purchase prices; goods without a barcode get a label.
Work through it from the top. Every step names its menu, who does it, what changes afterwards, and an example with figures.
The features in this guide come with the Bookshop business type package, except those marked extra. The shop's features show under Settings → Subscription, section This shop's features. If a menu is missing, contact the Vende team.
Tip: Lost on a page? Press the ? button at the top of that page. A short tour shows every field, on the Consignment Notes and Consignment Settlements too.
A new business
Who does what
This package holds three users, the owner included.
| Part of the shop | Job title in Vende | What they do and open |
|---|---|---|
| Owner | Owner | Every menu, also suppliers and consignors, purchase notes, Transactions → Consignment Notes, Transactions → Consignment Settlements, school prices, promotions, banking the till cash, payments, opening balances, Reports → Consignment, Reports → Cash Balance and Reports → Profit & Loss |
| Store room and shelves | Warehouse Admin | Products, receiving books from the distributor, labels, stocktakes and Reports → Stock |
| Cashier | Cashier | Selling at the till, customers, school notes, Transaction Details → Sale Lines |
Every role is explained in Roles and permissions.
1. Shop details and users
Done by the Owner: fill in Settings → Shop (name, address, WhatsApp, logo), then make the accounts in Settings → Users with the Job title from the table above. See Adding and managing users.
The people at Toko Buku Cahaya Ilmu: Bu Ratna (owner), Mas Fajar (store room and shelves, Warehouse Admin) and Dewi (cashier, Cashier).
2. Master data
A shop of this business type already has the product categories Textbooks, General Books, Children's Books, Religious Books and Writing Supplies, the unit Copy besides Pcs and the other built-in units, and the expense category Shopping Bags.
The shop's own books
Warehouse Admin: in Master Data → Products, make every book. Fill in the Code by scanning the ISBN barcode on its cover, so the cashier only has to scan the book.
| Product | Category | Base Unit | Selling Price |
|---|---|---|---|
| Buku Paket Matematika SMP Kelas 7 | Textbooks | Copy | Rp 85.000 |
| Novel Senja di Kota Tua | General Books | Copy | Rp 90.000 |
| Buku Cerita Si Kancil | Children's Books | Copy | Rp 35.000 |
| Pembatas Buku Kayu | Writing Supplies | Pcs | Rp 5.000 |
The Warehouse Admin does not see Cost Price, because the cost of goods shows only to the Owner and holders of Sensitive Reports. Leave it: the Owner's purchase notes in part 3 fill in their cost, for example Rp 65.000 for the maths book. See Cost price of goods.
Consignors and consigned books
- Owner: in Master Data → Suppliers, list the distributor CV Pustaka Nusantara with Payment Terms (days) 30, Grosir Alat Tulis Sinar, and both consignors: Pak Hendra Wijaya (an author) and Penerbit Aksara Mandiri. Consignors are listed as suppliers.
- Owner: in Master Data → Products, make Kumpulan Puisi Pelangi (General Books, Copy, Selling Price Rp 50.000). In the Consignment section, choose the Consignor Pak Hendra Wijaya, Consignor Share Fixed consignment price, and fill in Consignment Price Rp 40.000.
- Owner: make Buku Resep Masakan Rumahan (General Books, Copy, Selling Price Rp 80.000) with the Consignor Penerbit Aksara Mandiri, Consignor Share Shop commission (percent of the selling price), and Shop Commission 25. The consignor gets Rp 80.000 − 25% = Rp 60.000 for every book sold.
Consigned books have no cost price. They come in and go back only through a Consignment Note, never through a purchase or opening stock.
Schools and a promotion
- Owner: in Master Data → Customer Groups, make the group Sekolah with Group Discount 10%. See Setting up customer groups.
- Cashier: in Master Data → Customers, list SMP Tunas Bangsa with Group Sekolah and Payment Terms (days) 30.
- Owner: in Master Data → Promotions, make the promotion "Buy 3 children's books get 1 bookmark free": under What must be bought 3 Buku Cerita Si Kancil, under What is given free 1 Pembatas Buku Kayu, then switch on Active. See Automatic promotions.
3. Starting capital, purchases and consigned books
- The Owner records capital of Rp 10.000.000 into Bank BCA in Transactions → Finance → Owner's Capital, then moves Rp 300.000 to Cashier Cash as change money in Transactions → Finance → Cash Transfers.
- The Owner records the invoice of CV Pustaka Nusantara in Transactions → Purchases, without a payment: 30 Copies of Buku Paket Matematika SMP Kelas 7 × Rp 65.000 = Rp 1.950.000, 10 Novel Senja di Kota Tua × Rp 63.000 = Rp 630.000 and 12 Buku Cerita Si Kancil × Rp 24.000 = Rp 288.000, so Rp 2.868.000. Switch off All goods have been received, because the books are received in the store room.
- The Warehouse Admin (Mas Fajar) opens Transactions → Receive Goods, presses Receive on that invoice, checks the quantities that came, then presses Save Receipt. This screen shows no purchase prices.
- The Owner records the note of Grosir Alat Tulis Sinar, paid in full from Bank BCA: 50 Pcs of Pembatas Buku Kayu × Rp 2.000 = Rp 100.000.
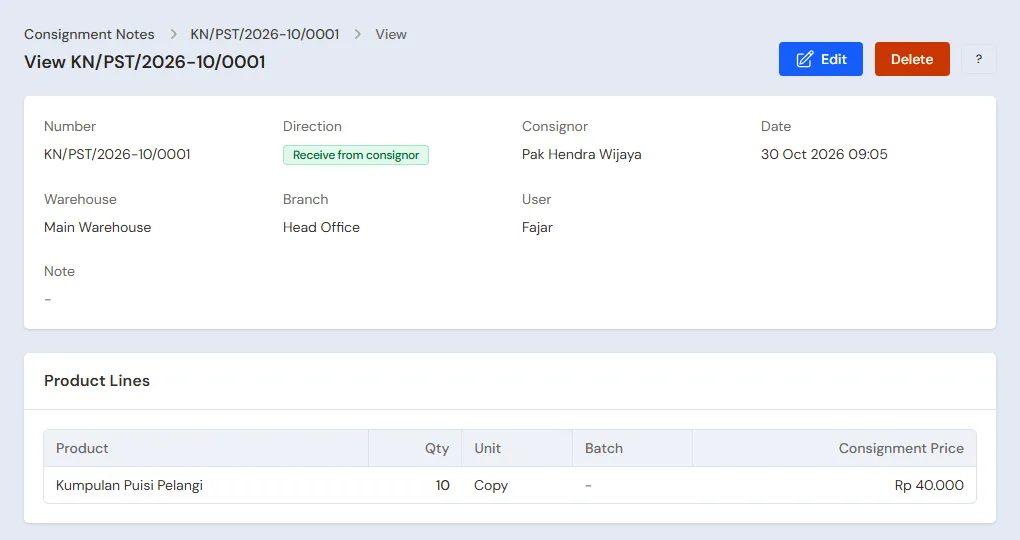
- The Owner records the consigned books in Transactions → Consignment Notes: choose the Consignor Pak Hendra Wijaya, add 10 Kumpulan Puisi Pelangi, then save. Make one more note for Penerbit Aksara Mandiri with 6 Buku Resep Masakan Rumahan. Their stock goes up with no cost and no payable.
- The Warehouse Admin prints labels for the bookmarks, which have no barcode, in Master Data → Print Labels: Source Purchase note, choose the Grosir Alat Tulis Sinar note under Document, press Take Goods, and choose Number of labels By quantity (unit on the document). 50 labels come out. See Printing price labels and barcodes.
See Recording a purchase note and Receiving goods that arrive in parts.
4. A day of selling
| Time | Who | Work |
|---|---|---|
| 09.00 | Cashier | Opens the till |
| All day | Cashier | Sells to walk-in buyers |
| Midday | Cashier | A school's textbook note |
| Closing | Owner | Banks the till cash |
Selling at the till
Open the till with New sale on the Dashboard, then scan the book's ISBN barcode. Consigned books are sold like any other book.
- Cashier (Dewi): a walk-in buyer buys Novel Senja di Kota Tua (Rp 90.000) and Kumpulan Puisi Pelangi (Rp 50.000), so Rp 140.000 in cash.
- Cashier: a mother buys 3 Buku Cerita Si Kancil, Rp 105.000. On saving, the promotion adds 1 free Pembatas Buku Kayu under Promotions. She pays with QRIS into Bank BCA.
- Cashier: a walk-in buyer buys Buku Resep Masakan Rumahan, Rp 80.000 in cash.
- Cashier: SMP Tunas Bangsa takes 20 Buku Paket Matematika SMP Kelas 7. Choose SMP Tunas Bangsa: every line gets the Group discount 10% at once, so 20 × Rp 85.000 − 10% = Rp 1.530.000. Press Pay, Unpaid, then Save transaction. The receivable falls due in 30 days.
See Recording sales on the till.
Closing and banking the till cash
The Owner (Bu Ratna) counts the drawer: Rp 300.000 change money + Rp 140.000 + Rp 80.000 = Rp 520.000. The Rp 220.000 is moved to Owner Cash in Transactions → Finance → Cash Transfers. A drawer holding less or more than counted is recorded in Transactions → Finance → Cash Adjustments. See Moving money between cash accounts.
5. Consignors, receivables and payables
Paying the consignors
At the end of every week the Owner pays the consignors for their books sold in Transactions → Consignment Settlements:
- Press the new button, choose the Consignor Pak Hendra Wijaya, and fill in Up To today.
- Goods Sold shows Kumpulan Puisi Pelangi: 1 copy, Rp 40.000.
- Under Pay Now, choose Paid From Cash Account Owner Cash and fill in Amount Paid Rp 40.000, then save.
- Do the same for Penerbit Aksara Mandiri: 1 Buku Resep Masakan Rumahan, Rp 60.000, paid from Owner Cash.
Every settlement makes one purchase note to the consignor. What is not paid now becomes a payable, paid later in Transaction Details → Purchase Payments. Consigned books that do not sell go back with Return to Consignor in Transactions → Consignment Notes.
In Profit & Loss, the consigned books sold still count as sales, Rp 50.000 and Rp 80.000, and the consignors' shares, Rp 40.000 and Rp 60.000, become cost of goods sold. So the shop earns Rp 30.000 on those two books.
Receivables, payables and expenses
- The Owner records the payment of SMP Tunas Bangsa in Transaction Details → Sale Payments: Rp 1.530.000 into Bank BCA. See Recording payments of unpaid notes.
- The Owner pays CV Pustaka Nusantara before the due date in Transaction Details → Purchase Payments: Rp 2.868.000. See Paying what you owe suppliers.
- Books with printing faults go back to the distributor with a purchase return. See Returning goods to a supplier.
- The Owner records rent, electricity, salaries and shopping bags in Transactions → Finance → Expenses. See Recording shop expenses.
The free bookmark of the promotion is not sold: its cost, Rp 2.000, is recorded as Promotion Expense.
6. Reports per job title
| Report | What it holds | Opened by | When |
|---|---|---|---|
| Reports → Stock | The stock of every book, the consigned ones too | Warehouse Admin | Every week |
| Transaction Details → Sale Lines | The books sold per note | Cashier | Every day |
| Reports → Consignment | Per consignor and book: received, sold, returned, still in the shop, and the consignor's share not settled yet | Owner | Every week |
| Reports → Cash Balance | The drawer, Owner Cash and the bank | Owner | Every day |
| Reports → Receivables | What every school still owes | Owner | Every week |
| Reports → Profit & Loss | Sales, cost of goods sold with the consignors' shares, expenses and Promotion Expense | Owner | Every month |
7. Checklists
- Every day: the Cashier scans the barcode of every book. The Owner counts the drawer and banks the money.
- Every week: the Owner makes a Consignment Settlement for every consignor, hands over their Consignment report, and collects from schools when due.
- Every month: the Warehouse Admin counts the stock with a stocktake. The Owner returns consigned books that have not sold for long and reads Profit & Loss. See Counting stock with a stocktake.
A running business
This part is for the team moving a running bookshop to Vende: books on the shelves, consigned books partly sold but not yet paid to their consignors, schools that still owe, and payables to the distributor. The order is always the same:
- Enter the master data.
- Practise transactions until every part is used to them.
- Empty the practice transactions.
- Enter the opening balances on the first day.
- Go live.
The opening balances come last on purpose, so the practice does not spoil their figures. The examples in this part use Toko Buku Cahaya Ilmu from the new business part.
1. Master data
Work through the parts Who does what, 1. Shop details and users and 2. Master data above. Also list every title still in stock, every consigned book with its consignor and share, every school that still owes, and every distributor still owed. Many titles are quicker to import from Excel. See Importing and exporting products with Excel. The master data is not deleted when the practice transactions are emptied.
2. Practice for the team
Work in a practice shop of the Bookshop type with the three accounts. Every step names who does it and what must show.
Practice 1: master data
- Owner: the shop details, the two users, the four suppliers and consignors, both consigned books, the group Sekolah and the promotion.
- Check: Dewi sees no purchase menus and no money reports.
- Warehouse Admin: the four products with their ISBN codes.
- Cashier: SMP Tunas Bangsa.
Practice 2: a day of selling
- Owner: capital of Rp 10.000.000, the transfer of Rp 300.000 to Cashier Cash, both purchase notes and both consignment notes as in part 3.
- Warehouse Admin: receive the books of the CV Pustaka Nusantara invoice, then print the 50 bookmark labels.
- Check: in Transactions → Receive Goods, that invoice shows no prices, and once received it no longer shows. Opened by the Warehouse Admin.
- Dewi (Cashier): the four notes as in part 4.
- Check: on the children's books note, the Promotions part holds 1 Pembatas Buku Kayu.
- Owner: the transfer of Rp 220.000 from Cashier Cash to Owner Cash, then both consignment settlements, paid from Owner Cash.
After Practice 2 this must show:
| Report | What must show | Opened by |
|---|---|---|
| Reports → Cash Balance | Cashier Cash Rp 300.000; Owner Cash Rp 220.000 − Rp 40.000 − Rp 60.000 = Rp 120.000; Bank BCA Rp 10.000.000 − Rp 300.000 − Rp 100.000 + Rp 105.000 = Rp 9.705.000 | Owner |
| Reports → Receivables | SMP Tunas Bangsa Rp 1.530.000 | Owner |
| Reports → Payables | CV Pustaka Nusantara Rp 2.868.000 | Owner |
| Reports → Consignment | Kumpulan Puisi Pelangi received 10, sold 1, still in the shop 9; Buku Resep Masakan Rumahan received 6, sold 1, still in the shop 5; not settled Rp 0 | Owner |
| Reports → Stock | Buku Paket Matematika SMP Kelas 7 10, Novel Senja di Kota Tua 9, Buku Cerita Si Kancil 9, Pembatas Buku Kayu 49 | Warehouse Admin |
| Reports → Profit & Loss | Net sales Rp 140.000 + Rp 105.000 + Rp 80.000 + Rp 1.530.000 = Rp 1.855.000, cost of goods sold Rp 1.535.000, Promotion Expense Rp 2.000 | Owner |
Cost of goods sold: the maths books 20 × Rp 65.000 = Rp 1.300.000, the novel Rp 63.000, the children's books 3 × Rp 24.000 = Rp 72.000, and the consignors' shares Rp 40.000 + Rp 60.000.
Practice 3: opening balances
Enter the opening balances with the example of part 4 below, check them as in part 5, then empty them again.
3. Emptying the practice transactions
Done by the Owner in Settings → Empty Transactions, button Empty All Transactions. Sale notes, purchases and their goods receipts, consignment notes, consignment settlements, stock adjustments, payments, cash transfers, capital, expenses and opening balances are deleted. Products with their consignors and shares, promotions, customer groups, customers, suppliers, cash accounts, users and settings stay. Vende makes a full backup first. See Emptying transactions or all data.
4. Opening balances
Done by the Owner in Settings → Opening Balances on the morning of the first day, with As of that day, before the shop opens. See Entering opening cash, stock, receivables and payables.
- Opening Stock: one row per title the shop owns, for example Novel Senja di Kota Tua 7 Copies at Rp 63.000. The Warehouse Admin's count gives the quantities.
- Opening Receivables: SMP Tunas Bangsa Rp 765.000 with its due date.
- Opening Payables: CV Pustaka Nusantara Rp 1.500.000.
- Opening Cash: the money counted in every account, for example Cashier Cash Rp 300.000 and Bank BCA Rp 6.000.000.
Consigned books already in the shop
Consigned books cannot go into Opening Stock: Vende refuses them, because they belong to the consignor. Record them in these two ways on the first day:
- Books still on the shelf: the Owner records them in Transactions → Consignment Notes as in part 3, for example 8 Kumpulan Puisi Pelangi from Pak Hendra Wijaya. Their stock goes up with no cost and no payable.
- Books already sold but not yet paid to the consignor: write the consignor's share as that consignor's Opening Payables, for example 3 books × Rp 40.000 = Rp 120.000 for Pak Hendra Wijaya.
The first Consignment Settlement counts only the books sold since the first day. The opening payable of Rp 120.000 is paid on its own in Transaction Details → Purchase Payments, so nothing is counted twice.
5. Check before going live
| Report | What must show | Opened by |
|---|---|---|
| Reports → Cash Balance | The money counted in every account | Owner |
| Reports → Stock | The count of every title, and 8 Kumpulan Puisi Pelangi | Warehouse Admin |
| Reports → Consignment | Kumpulan Puisi Pelangi received 8, still in the shop 8, not settled Rp 0 | Owner |
| Reports → Receivables | SMP Tunas Bangsa Rp 765.000 | Owner |
| Reports → Payables | CV Pustaka Nusantara Rp 1.500.000; Pak Hendra Wijaya Rp 120.000 | Owner |
The figures differ? The Owner corrects the row in Settings → Opening Balances before any real transaction is recorded. A wrong consignment note is changed from its own page.
6. Going live
From that day every sale, purchase, goods receipt, consigned book, settlement and payment is recorded in Vende as in the new business part, with the same checklist. In the first week the Warehouse Admin matches Reports → Stock with the shelves, and the Owner checks that Reports → Profit & Loss only holds sales and costs since the first day.